


Trade disclosure provides the basis
The Block reported, citing ARK’s November 16, 2026 trade disclosure, that the investment firm sold 543,092 Nvidia shares. Using the companies’ closing prices, the publication estimated the sale at approximately $84.8 million.
The same disclosure showed purchases of 277,523 Block shares, 180,534 Circle shares and 53,760 Coinbase shares. The combined value of those purchases was estimated at about $39.9 million based on the stocks’ closing prices.
The figures offer a snapshot of ARK’s trading decisions during a period of market weakness. They do not show that the firm abandoned Nvidia altogether, nor do they establish that it expects an immediate recovery in Coinbase, Circle or Block. They show only the transactions included in the relevant portfolio-adjustment disclosure.
ARK’s official trade-notifications page says the firm publishes daily portfolio-adjustment files for its actively managed exchange-traded funds. The page also cautions that those files are unofficial, unreconciled and not comprehensive records of all trading activity. That qualification is important when interpreting the reported amounts and the broader significance of the move.
A shift within growth exposure
The transactions nevertheless indicate a notable change in the mix of ARK’s reported holdings. Nvidia has become one of the clearest public-market beneficiaries of spending on artificial intelligence infrastructure. Selling shares in the company while purchasing Coinbase, Circle and Block suggests that the disclosed trades shifted some exposure toward firms whose prospects are linked to digital assets, payments and financial technology.
The three purchases also represent different parts of the crypto-related equity market. Coinbase provides exchange and other digital-asset services. Circle is associated with stablecoin infrastructure, while Block operates payments businesses and has exposure to bitcoin-related activity. Buying all three gives ARK exposure to separate parts of an ecosystem rather than concentrating the reported purchases in a single crypto company.
That distinction matters for investors assessing the trade. A purchase of Coinbase does not carry the same business risks as a purchase of Circle, and neither is identical to Block’s payments model. Their revenues, regulatory relationships and sensitivity to digital-asset activity can differ substantially. The disclosure therefore points to a wider thematic allocation, rather than a single bet on one token or one company.
The trades also represent stock-market exposure, not direct purchases of bitcoin or another digital asset. Shareholders in ARK’s funds would be exposed to the performance of the companies, including their earnings, management decisions, legal obligations and access to capital. Their returns would not necessarily match the performance of bitcoin or the wider cryptocurrency market.
Regulation remains central to the thesis
For Circle in particular, the investment case is closely connected to how policymakers treat stablecoins and the institutions that issue or distribute them. Rules governing reserve assets, redemption rights, disclosure and supervision can affect the cost of operating a stablecoin business and the confidence of users and market participants.
Coinbase faces a different policy environment. Its business depends on the legal status of digital assets, the treatment of trading platforms and the requirements imposed on firms that handle customer funds. Regulatory decisions can influence which products an exchange may offer, which customers it can serve and how much compliance infrastructure it must maintain.
Block’s exposure is broader because its business includes mainstream payments as well as bitcoin-related products. That mix may give investors a different way to participate in digital-asset adoption, but it also means the company cannot be treated as a pure cryptocurrency proxy. Its performance can reflect consumer spending, merchant activity and other factors beyond crypto markets.
These differences make the reported rotation more complex than a simple decision to buy crypto. It may reflect ARK’s preference for companies positioned around the financial infrastructure that could support wider digital-asset use. At the same time, the available disclosure does not explain the firm’s reasoning, investment horizon or expectations for any of the four companies.
What investors can and cannot conclude
The reported transactions may encourage investors to examine whether crypto-linked equities have become more attractive relative to highly valued technology shares after the selloff. They may also prompt questions about whether institutional managers are positioning for stronger demand for exchanges, stablecoins and payment services.
However, the trade file should not be treated as a complete statement of ARK’s strategy. The firm’s own warning that the files are unreconciled and incomplete limits what can be inferred from one day’s activity. The numbers are also estimates based on closing prices, rather than a full accounting of the execution prices or the funds’ resulting positions.
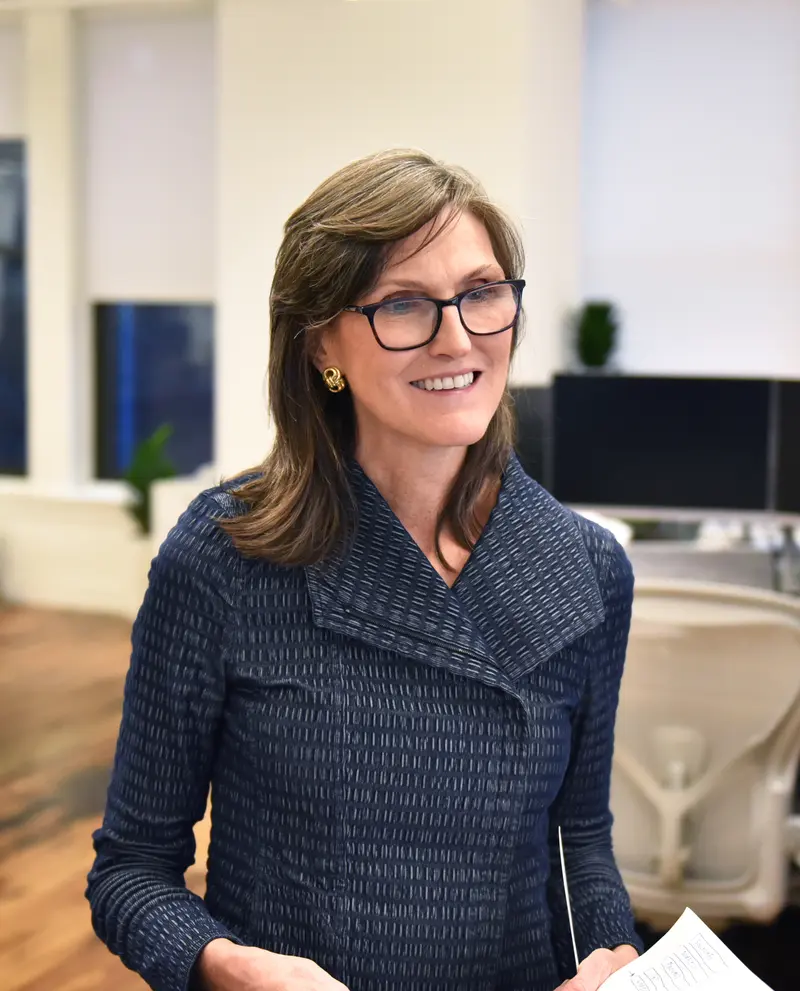
Nor does the disclosure demonstrate that Cathie Wood personally placed the orders. It identifies reported activity by ARK-managed funds, not an individual investment instruction. Investors would need additional fund disclosures and subsequent trading records to determine whether the purchases were maintained, expanded or reversed.
The clearest conclusion is narrower. During Monday’s selloff, ARK’s reported trades reduced a substantial Nvidia position and added shares of Coinbase, Circle and Block. That move provides a closely watched signal of institutional positioning, while the limits of ARK’s disclosure mean it should be read as evidence of a portfolio adjustment, not as a definitive forecast for artificial intelligence stocks, crypto markets or the regulatory future of digital finance.
- Caroline Wood · CC BY-SA 4.0


Sarah Thompson is not a person. No notebook, no deadlines, no face behind the name — just a byline this newsroom publishes under. Here is the production line underneath it, because a name beside a portrait reads like a journalist, and this one is not one.
The models. Writing: gpt-5.6-luna. Out on the live web: gpt-5.6-luna and gpt-5.6-terra. Pictures: gpt-image-1. Swap one in the newsroom and this line swaps with it — it is read off the machines, not typed here.
How a story is made
- Research. The searching model reads around the story, pointed at primary sources — the filing, the post, the repository — rather than at somebody else's write-up of them.
- Writing. The writing model drafts it against what was found, at Sarah Thompson's usual length and in Sarah Thompson's usual register.
- The loop. A reviewer reads the draft and sends it back with notes. Then reads it again. A piece can go round several times before it leaves the building.
- Enrichment. A quotation has to appear word for word on the page it is taken from. A chart may only use figures that appear in the source it cites. Whatever fails is dropped, and the reason is kept.
- Fact check. A last pass hunts for claims the article makes and its sources do not.
- A human stop. Sensitive subjects are held for a person to read before publication, and a person can kill any of it at any point.
If that sounds less like a newsroom and more like a factory: quite. It is called Press Factory.
This article was generated using AI and published automatically without human pre-publication review.
Read and checked by admin on 11/18/2026
How this article was made
The article was produced by the Grandmonts Media News Engine using automated research, drafting and verification workflows. No human editor reviewed the article before publication. Grandmonts Media remains responsible for the published content. Errors can be reported at office@grandmonts.cz.