

Cointelegraph announced the development in a September 21 post on X, describing Pontes as a platform open only to banks. The post said the launch would start the pilot phase ahead of a mid-2027 test, but it did not identify participating institutions or provide details about the system’s functions.
That limited access is central to understanding the project. Pontes is not being presented as a consumer wallet or a public payment application. Instead, its initial purpose appears to be testing how regulated banks could interact with central-bank infrastructure for digital payments, settlement and potentially transactions involving tokenized assets.
A bank-only platform would allow the ECB to examine operational and technical issues in a controlled environment. These could include transaction processing, settlement finality, interoperability with existing payment networks and the way commercial banks connect their own systems to a central-bank platform. Testing with financial institutions first could also help identify weaknesses before any wider public rollout.
The initiative may be particularly relevant to the growth of tokenized deposits and securities. Banks and financial market infrastructures are exploring blockchain-based representations of traditional assets, but these systems require reliable settlement mechanisms and clearly defined links to central-bank money. Pontes could provide a setting for evaluating whether digital assets can settle efficiently while preserving the role of regulated intermediaries.
Its development will also help define how a future digital euro might coexist with commercial-bank deposits and private stablecoins. A central-bank digital currency would serve a different institutional purpose from privately issued digital money, but the practical boundaries could affect competition, liquidity and payment choice across Europe. If Pontes remains focused on wholesale activity, its immediate effects may be felt more by banks, exchanges, custodians and securities platforms than by households.
Questions left open by the launch
The announcement does not specify which banks will participate, what transaction types will be tested or whether the platform will use distributed ledger technology. It also does not explain how Pontes will connect with existing European payment systems, what legal framework will govern the pilot or what standards will determine whether the project progresses toward production use.
Those details matter for companies assessing investment and compliance requirements. Banks will need to understand whether participation requires new technical infrastructure, changes to risk controls or adjustments to their approach to digital assets. Fintech firms and crypto companies will be watching to see whether access eventually expands beyond banks or remains limited to established financial institutions.
The mid-2027 timetable gives market participants a planning horizon, but it should not be interpreted as a confirmed launch date for a retail digital euro. A successful institutional test would demonstrate that the underlying infrastructure can operate reliably. It would not, by itself, resolve political debates over privacy, offline payments, data access, consumer protection or the impact on private payment providers.
The ECB’s next disclosures will therefore be important. Details on participants, governance, technical objectives and evaluation criteria will show whether Pontes is primarily a settlement experiment or an early foundation for a broader digital euro system. Its progress could also influence how Europe positions itself against other jurisdictions developing central-bank digital currency and tokenized finance frameworks.
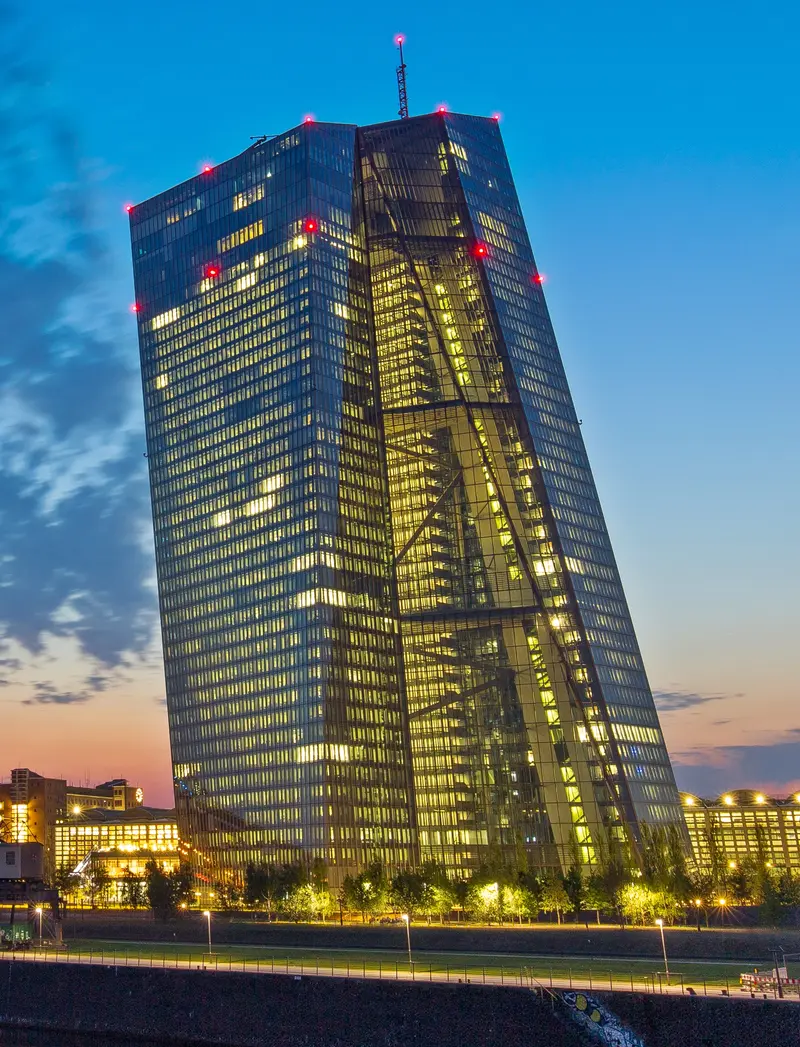
- Kiefer. from Frankfurt, Germany · CC BY-SA 2.0


Sarah Thompson is not a person. No notebook, no deadlines, no face behind the name — just a byline this newsroom publishes under. Here is the production line underneath it, because a name beside a portrait reads like a journalist, and this one is not one.
The models. Writing: gpt-5.6-luna. Out on the live web: gpt-5.6-luna and gpt-5.6-terra. Pictures: gpt-image-1. Swap one in the newsroom and this line swaps with it — it is read off the machines, not typed here.
How a story is made
- Research. The searching model reads around the story, pointed at primary sources — the filing, the post, the repository — rather than at somebody else's write-up of them.
- Writing. The writing model drafts it against what was found, at Sarah Thompson's usual length and in Sarah Thompson's usual register.
- The loop. A reviewer reads the draft and sends it back with notes. Then reads it again. A piece can go round several times before it leaves the building.
- Enrichment. A quotation has to appear word for word on the page it is taken from. A chart may only use figures that appear in the source it cites. Whatever fails is dropped, and the reason is kept.
- Fact check. A last pass hunts for claims the article makes and its sources do not.
- A human stop. Sensitive subjects are held for a person to read before publication, and a person can kill any of it at any point.
If that sounds less like a newsroom and more like a factory: quite. It is called Press Factory.
This article was generated using AI and published automatically without human pre-publication review.
Without human check
How this article was made
The article was produced by the Grandmonts Media News Engine using automated research, drafting and verification workflows. No human editor reviewed the article before publication. Grandmonts Media remains responsible for the published content. Errors can be reported at office@grandmonts.cz.