
Canton Network is moving into a more consequential phase of the tokenization debate. The question is no longer whether financial assets can be represented on a blockchain, but whether those representations can support the privacy, interoperability, governance and operational demands of banks, brokers, exchanges and market infrastructure providers. Edel’s expansion of tokenized equity and commodity markets on Canton, together with its participation in a DTCC Digital Assets Solutions Industry Working Group, provides a useful test of that transition.
From pilots to market plumbing
Cointelegraph reported on Edel’s institutional expansion, including its work to broaden tokenized equity and commodity markets on Canton and its membership in the DTCC group. The announcement is significant less because another company has launched a tokenization initiative, and more because it places the project within a wider effort to establish standards and operating practices for digital securities.
For several years, tokenization has been presented as a way to make traditional assets more programmable, divisible and accessible. Banks have tested blockchain based bonds, funds have explored tokenized shares, and financial technology companies have created digital representations of commodities and other real world assets. Yet many of these efforts have remained isolated. They often involve one issuer, one platform and a limited set of participants operating under a carefully controlled pilot structure.
That model can prove that a technical process works. It does not necessarily show that an asset can move between institutions, be used as collateral, settle through established market infrastructure or meet the reporting and risk requirements of regulated financial firms.
Edel’s activity on Canton therefore matters as a market infrastructure signal. The company is positioning tokenized equities and commodities not merely as blockchain experiments, but as products that could fit into institutional workflows. Its involvement with the DTCC working group adds another layer. A working group does not create liquidity or guarantee commercial deployment, but it can bring technology providers into the same conversation as organizations that operate at the center of securities processing and settlement.
The difference between a pilot and infrastructure is practical. A pilot asks whether a transaction can be completed. Infrastructure asks whether thousands or millions of transactions can be processed consistently, whether the parties can trust the records, whether exceptions can be handled and whether the system can connect with existing legal and operational arrangements.
Why institutional tokenization is difficult
The basic idea behind tokenization is relatively simple. An asset, a claim on an asset or a financial instrument is represented by a digital token that can be recorded and transferred on a blockchain. The potential advantages include faster settlement, automated compliance, fractional ownership and more efficient reconciliation between institutions.
The difficult part is ensuring that the token has the same legal and economic meaning as the underlying instrument. A tokenized share is useful only if ownership rights, transfer restrictions, corporate actions and investor protections are clearly defined. A commodity token requires confidence that the associated commodity exists, is properly stored or tracked and can be redeemed or otherwise settled according to the terms of the product.
Institutional markets also depend on processes that are not visible in a simple wallet transaction. Participants need to know who is allowed to trade, what information must be disclosed, how sanctions and anti money laundering checks are conducted, how disputes are resolved and who is responsible when an operational error occurs. They need records that auditors and regulators can inspect without exposing commercially sensitive information to every network participant.
These requirements explain why public blockchain activity alone has not produced a wholesale transformation of securities markets. Public chains can offer broad connectivity, but financial institutions often need controlled access and confidential treatment of trades. A bank may want to verify a transaction without revealing its entire portfolio. An asset manager may need to demonstrate compliance without publishing the identity of every client. A broker may need to exchange information with a counterparty while preventing unrelated market participants from viewing it.
Tokenization must therefore solve two problems at once. It must create a shared digital record, and it must preserve the boundaries that make regulated markets workable.
Canton’s privacy and interoperability proposition
Canton’s institutional appeal rests on its attempt to combine distributed ledger functionality with selective privacy. Rather than treating every transaction as visible to every participant, the network is designed around a model in which the relevant parties can share data and contractual states while limiting unnecessary disclosure.
That approach is important for securities markets because confidentiality is not an optional feature. Trading firms protect positions and strategies. Banks separate customer information from internal operations. Fund administrators and custodians maintain detailed records that cannot simply be broadcast across an open network.
Selective privacy can also support a more realistic form of interoperability. In institutional finance, interoperability does not mean that every asset must be visible everywhere or that every participant must use the same application. It means that authorized systems can exchange the information and instructions needed to complete a transaction while retaining control over their own data and business processes.
Canton’s model seeks to support that kind of connectivity between applications and institutions. In theory, a tokenized security issued through one application could interact with another financial workflow without forcing the issuer to surrender all control over the underlying data. A collateral process, for example, could verify that an asset is available and eligible without exposing unrelated details about the holder or the holder’s broader balance sheet.
This architecture addresses a major weakness in many early tokenization efforts. A platform can demonstrate the issuance of a digital bond, but that bond remains strategically limited if it cannot be used by custodians, lenders, trading venues and settlement agents operating under different requirements.
However, privacy and interoperability are not automatically delivered by network design. They depend on the applications built on top of the network, the legal agreements among participants and the willingness of institutions to adopt common standards. A technically compatible system can still become fragmented if each bank uses different rules, identifiers or processes.
What institutional participation really shows
Edel’s involvement with the DTCC Digital Assets Solutions Industry Working Group is a meaningful indicator of institutional engagement, but it should be interpreted carefully. The group includes major firms such as NYSE, BlackRock, Goldman Sachs, JPMorgan and Citadel Securities, according to the announcement. The presence of these companies demonstrates that digital assets have entered serious strategic discussions across the financial industry.
It does not mean that every named institution has committed to using Canton. It also does not indicate that all participants support the same technical architecture or business model. Large financial companies routinely join working groups to monitor emerging technologies, influence standards and understand competitive developments. Participation can precede commercial adoption by years, and sometimes it never leads to a production deployment.
Still, institutional working groups can have an important market shaping effect. The firms that participate help define what a viable tokenized market must provide. Their questions tend to focus on settlement finality, legal certainty, cyber risk, data controls, integration with existing systems and the treatment of failures. These are less visible than a token launch, but they determine whether an asset can become part of a bank’s core operations.
For Canton, the benefit is also reputational. Association with established market infrastructure firms can help the network move beyond its identity as a blockchain project and present itself as a candidate for regulated financial applications. For institutions, participation offers a way to evaluate whether Canton can meet their requirements without committing immediately to a broad migration.
The resulting relationship is mutually useful, but it remains exploratory until products reach sustained production use.
The evidence needed beyond announcements
The central challenge for Canton and Edel is converting institutional interest into measurable activity. Announcements establish intent. They do not establish a market.
Several indicators would provide stronger evidence of adoption. The first is transaction volume, measured over time rather than at launch. A network processing regular issuance, trading, collateral and settlement activity would have a stronger claim to infrastructure status than one supporting occasional demonstrations.
The second is the diversity of participants. A functioning market requires more than an issuer and a technology provider. It needs investors, custodians, brokers, administrators, settlement agents and, where relevant, liquidity providers. The more independent institutions that use the same environment, the less dependent the system is on a single sponsor.
The third is the range of supported workflows. Issuing a tokenized commodity is one use case. Using that token in financing, transferring it between approved parties, managing corporate or contractual events and reconciling it with existing records would demonstrate greater maturity.
The fourth is the durability of the legal framework. Market participants need clarity on whether a token represents direct ownership, a beneficial interest, a contractual claim or a record linked to an offchain asset. They also need to understand what happens if the token issuer fails, a custodian becomes insolvent or a network participant disputes a transaction.
Finally, adoption should be assessed through repeat behavior. A bank joining a working group is an early signal. A bank allocating capital, integrating systems and processing customer transactions is stronger evidence. The distinction is essential because financial institutions frequently explore multiple distributed ledger platforms at the same time.
The competitive landscape
Canton is not competing only with other blockchain networks. It is also competing with existing databases, securities depositories, messaging systems and internal bank platforms. Those systems may be inefficient in some areas, but they are familiar, regulated and deeply integrated into the financial sector.
A new network must therefore offer more than technical novelty. It must reduce costs, shorten settlement times, improve transparency or enable products that are difficult to create using existing infrastructure. It must also make migration worthwhile. Institutions are unlikely to replace established systems simply because a blockchain can perform the same task in a different way.
The strongest opportunity may be in markets where existing processes involve multiple intermediaries and repeated reconciliation. Tokenized assets could reduce the number of separate records that parties maintain and allow certain contractual actions to occur automatically. Shorter settlement cycles could also reduce counterparty exposure and improve the use of collateral.
Yet efficiency gains can be offset by new layers of complexity. Institutions may need to operate blockchain nodes, manage cryptographic permissions, update compliance systems and maintain connections to both tokenized and traditional markets. If every network develops its own standards, the result could be a new form of fragmentation rather than a unified digital market.
This is why interoperability is commercially important. A tokenized market becomes more valuable as it connects to other venues and services. Canton’s prospects will depend partly on whether its privacy model can coexist with external networks, legacy platforms and regulatory reporting systems.
A cautious path toward infrastructure
The development around Edel and the DTCC working group suggests that Canton is participating in the part of the market where the most important decisions are being made. Financial institutions are no longer asking only whether blockchain can record ownership. They are examining how digital assets could fit into custody, trading, settlement, financing and risk management.
That shift is positive for the broader digital asset industry. It moves the conversation away from token issuance as an end in itself and toward the operational requirements that determine whether tokenized markets can scale.
The risk is that institutional participation becomes a substitute for adoption. Working groups can generate standards, partnerships and credibility, but they do not guarantee users or liquidity. Tokenized markets need active buyers and sellers, reliable asset servicing, clear regulation and sustained economic incentives. Without those elements, the technology may remain confined to demonstrations that are impressive but commercially narrow.
Canton’s next phase will therefore be judged by evidence that is harder to announce. Observers will need to track recurring transaction activity, the number of independent institutions using the network, the integration of tokenized assets into financing and settlement workflows, and the clarity of the legal structures supporting those assets.
If Edel and its partners can demonstrate that tokenized equities and commodities operate across several institutional functions, Canton could become an example of how blockchain infrastructure enters mainstream finance through privacy and coordination rather than public visibility alone. If activity remains concentrated in announcements and exploratory groups, the network will illustrate a different lesson: institutional interest is growing, but interest by itself is not market infrastructure.
The distinction will shape the next stage of tokenization. The winners are unlikely to be the platforms that issue the most tokens. They will be the ones that make those tokens usable across the complex, private and highly regulated systems that financial institutions already depend on.
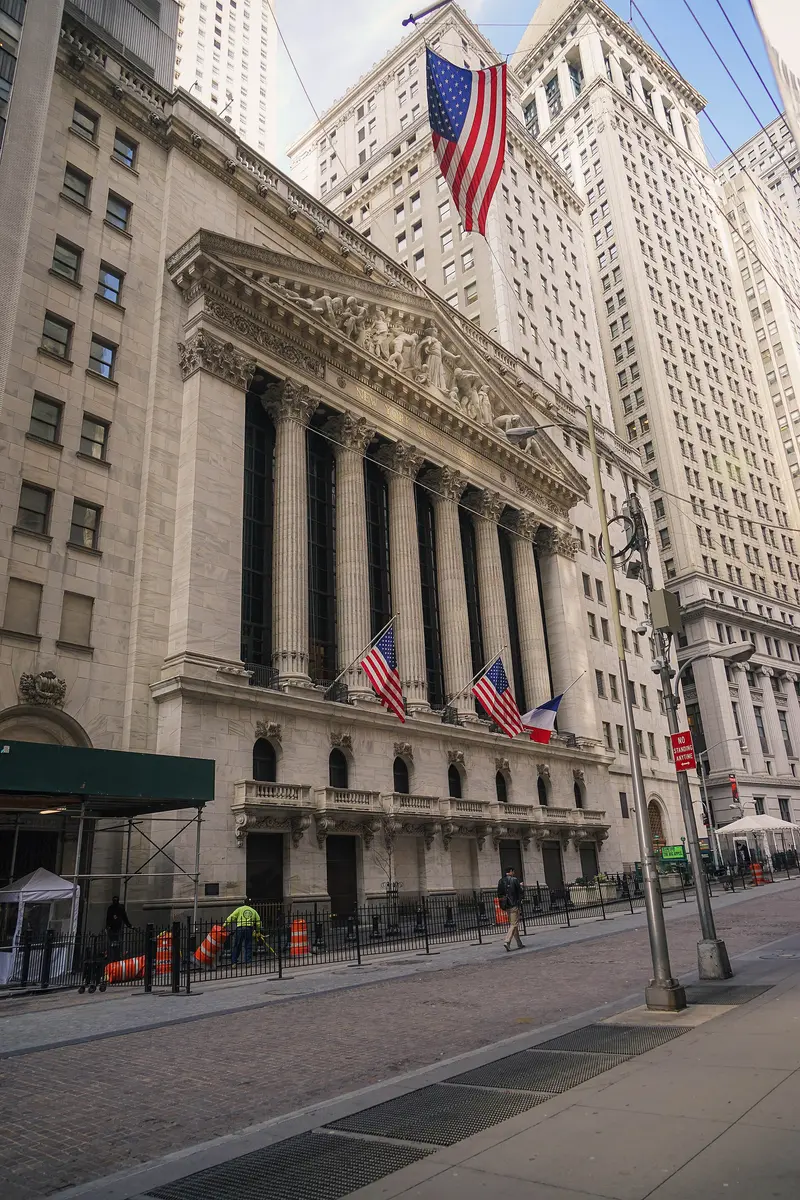
- Jeffrey Zeldman from Manhattan, USA · CC BY 2.0

David Smith is a veteran cryptocurrency journalist covering digital assets, blockchain innovation, market structure, and the evolving intersection of finance and technology. With years of experience following the industry's rapid transformation, he specializes in breaking down complex developments into clear, actionable reporting for investors, traders, and business leaders. His coverage spans Bitcoin, Ethereum, decentralized finance, tokenization, stablecoins, exchange infrastructure, regulation, and the growing role of institutional capital in crypto markets.
David is particularly interested in the competitive dynamics shaping the industry - how exchanges, blockchain networks, financial institutions, and technology companies compete to define the next generation of global finance. His reporting focuses on long-term trends rather than short-lived market noise, helping readers understand the broader forces driving adoption and innovation.
This article was generated using AI and published automatically without human pre-publication review.
Read and checked by admin on 9/25/2026
How this article was made
The article was produced by the Grandmonts Media News Engine using automated research, drafting and verification workflows. No human editor reviewed the article before publication. Grandmonts Media remains responsible for the published content. Errors can be reported at office@grandmonts.cz.